The best working capital solution for an importer is usually a combination of financing that covers each stage of the cash gap:purchase order financing or trade payable financing to pay your overseas supplier, then invoice factoring to turn your customers' invoices into cash once the goods are delivered.
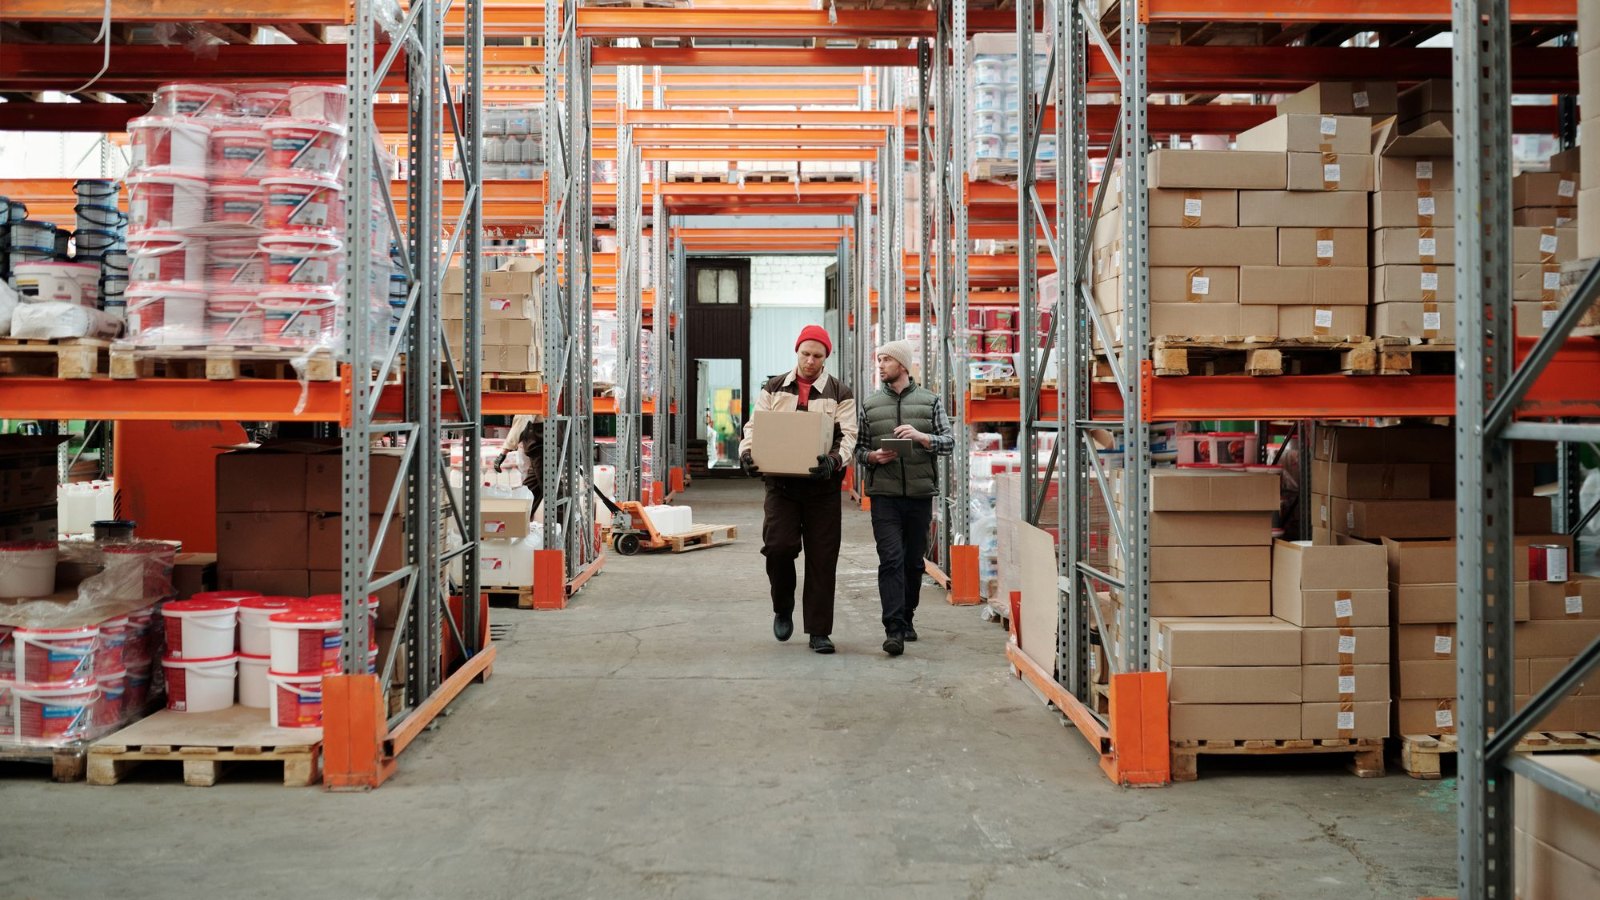
Importers face a classic cash conversion problem. Your supplier wants a deposit or full payment before the goods ship. The goods spend weeks at sea and in customs. Then your customers, often retailers, distributors or wholesalers, take 30 to 90 days to pay. A bank line of credit can bridge that gap if you qualify, but many importers need financing that is based on their orders and their customers rather than on their balance sheet.
The Importer's Cash Gap, Step by Step
Here is what a typical import cycle looks like, and which type of financing covers each step.
An illustrative import cycle. Each stage of the cash gap has a financing tool that fits it.
Stage
What happens
The cash problem
Financing that fits
1. You place the order
Your customer sends you a purchase order. You order the goods from your overseas supplier.
The supplier asks for a deposit or full payment before production or shipment.
Purchase order financing or trade payable financing
2. The goods ship
The goods are produced, shipped, cleared through customs and delivered.
Your cash is tied up in inventory that is in-transit.
Purchase order financing can also cover shipping and applicable duty fees.
3. You invoice your customer
The goods are delivered and you send the invoice on 30 to 90 day terms.
You have to wait for your customer to pay before you can fund the next order.
Invoice factoring advances most of the invoice 24 Hrs. after delivery.
4. Your customer pays
Your customer pays the invoice.
None. The cycle closes.
The financing is repaid and you receive the balance.
Your supplier, for goods, shipping and applicable duty fees
Importers with a confirmed order from a creditworthy customer who can't fund the supplier payment
U.S. companies with at least one year in business and tax returns. $100,000 minimum recurring transaction, at least 25% profit on the deal, and a factoring account with us. Rates usually 1.5% to 5%.
Your working capital, by advancing the value of your customers' invoices
Importers selling to creditworthy U.S. retailers, distributors and wholesalers on 30 to 90 day terms
Advances of 75% to 85% depending on the industry, rates from 0.69% to 1.59%, and credit and cargo insurance available. Import and export programs start at $150,000 in monthly sales.
Letter of credit
A bank's guarantee that your supplier will be paid once the shipping documents are presented
Suppliers who require bank-backed payment security
General working capital, secured by your receivables and inventory
Established importers with strong financials
Usually the lowest cost if you qualify, but approval depends on your financial statements, and goods still in transit may not count as collateral.
Example: Funding a $200,000 Import Order
Here is a hypothetical example to show how the pieces fit together. Actual advance rates, fees and terms depend on your industry, your customers and your transaction.
A U.S. importer receives a $300,000 purchase order from a national retailer. The goods cost $200,000 from an overseas supplier, who wants payment before shipment. The retailer pays on 60-day terms after delivery.
Day 0: Purchase order financing pays the $200,000 to the supplier. The importer's profit on the deal is $100,000, or 33%, above the 25% minimum.
Day 60: The goods arrive and are delivered to the retailer. The importer sends a $300,000 invoice.
Day 60: The invoice is factored. At an 85% advance, $255,000 becomes available, which repays the purchase order financing and its fees and leaves cash for the next order.
Day 120: The retailer pays the invoice. The remaining balance, minus the factoring fees, is released to the importer.
Without financing, the importer would have had to find $200,000 of its own cash and wait four months to get it back. With financing, the order was funded by the deal itself.
Why Not Just Use a Letter of Credit or a Bank Loan?
Letters of credit and bank lines are still common, and they can be the cheapest option for companies that qualify. But they have limits for growing importers:
Letters of credit need a bank. The bank issues the guarantee based on your creditworthiness, and smaller companies are often asked for cash collateral.
Bank lines depend on your financials. Approval is based on your profits, your balance sheet and your time in business.
Goods in transit are hard to borrow against. Inventory that is still at sea or in customs often doesn't count toward a borrowing base.
Purchase order financing, In-Transit Inventory Finance, trade payable financing and factoring are based on your orders, your suppliers and your customers. That is why they can grow with your sales.
Real Example: Paying Suppliers Faster Without Changing Your Terms
Vendor Pay Express is a supplier payment platform run by an affiliate of 1st Commercial Credit, also led by Raul Esqueda. It pays suppliers early while buyers keep their negotiated payment terms. In one transaction, 1st Commercial Credit used it to fund a Brazilian produce exporter selling to U.S. buyers: once a buyer approved an invoice, the exporter was paid promptly and the buyer kept its usual payment schedule (read the full story).
What You Need to Qualify
Creditworthy customers. Retailers, distributors, wholesalers or other businesses with a good record of paying on time.
A real order or invoice. A purchase order from your customer for purchase order financing, or invoices for delivered goods for factoring.
A healthy margin. For purchase order financing, at least 25% profit on the transaction.
Volume that fits the program. A $100,000 minimum for purchase order transactions and for trade payable spend, and $150,000 in monthly sales for import and export factoring programs.
Can I get financing to pay my overseas supplier before shipment?
Yes. Purchase order financing pays your supplier for goods, shipping and applicable duty fees when you have a purchase order from a creditworthy customer. Trade payable financing can also pay your international suppliers and let you repay on your standard terms. We do not offer deposits to suppliers to start a production order but may offer a letter of credit to secure production.
What is the difference between purchase order financing and trade payable financing?
Purchase order financing is tied to a specific customer order and is repaid when that order is invoiced and paid. Trade payable financing is a credit line for paying your suppliers, which you repay on your standard terms while offer early payment as an option to vital suppliers.
Can importers factor invoices from U.S. retailers?
Yes. 1st Commercial Credit finances importers that sell to creditworthy U.S. retailers, distributors and wholesalers, with advances of 75% to 85% depending on the industry and rates from 0.69% to 1.59%.
Is trade payable financing an alternative to a letter of credit?
It can be. Instead of a bank guaranteeing payment, a trade payable finance company pays your supplier directly, as long as the supplier accepts the payment terms. You then repay the finance company on your standard terms.
A letter of credit does carry less risk, though. Funds are only released once the supplier delivers, so if they don’t perform, you aren’t out the money. Also, not every supplier will qualify for trade payable financing: those that aren’t financially strong may be turned down.
How fast can I set up import financing?
With trade payable financing, you must set up a factoring agreement 1st with 1st Commercial Credit. Buyers should have recurring orders and previous transaction history. Invoice factoring is usually set up in 3 to 5 working days.
Close Your Import Cash Gap
1st Commercial Credit has been in business since 2002 and has funded more than 3,800 clients. If your suppliers want to be paid before your customers pay you, request a quote or call 1 (800) 876-6071.
Import Financing: How to Pay Overseas Suppliers Before Your Customers Pay
Suppliers want to be paid before your customers pay?
Close your import cash gap. Purchase order financing, trade payable financing and invoice factoring from 1st Commercial Credit fund every stage, from supplier payment to customer payment.