
As Your Business Grows
We Deliver The FUNDS
We Deliver The FUNDS


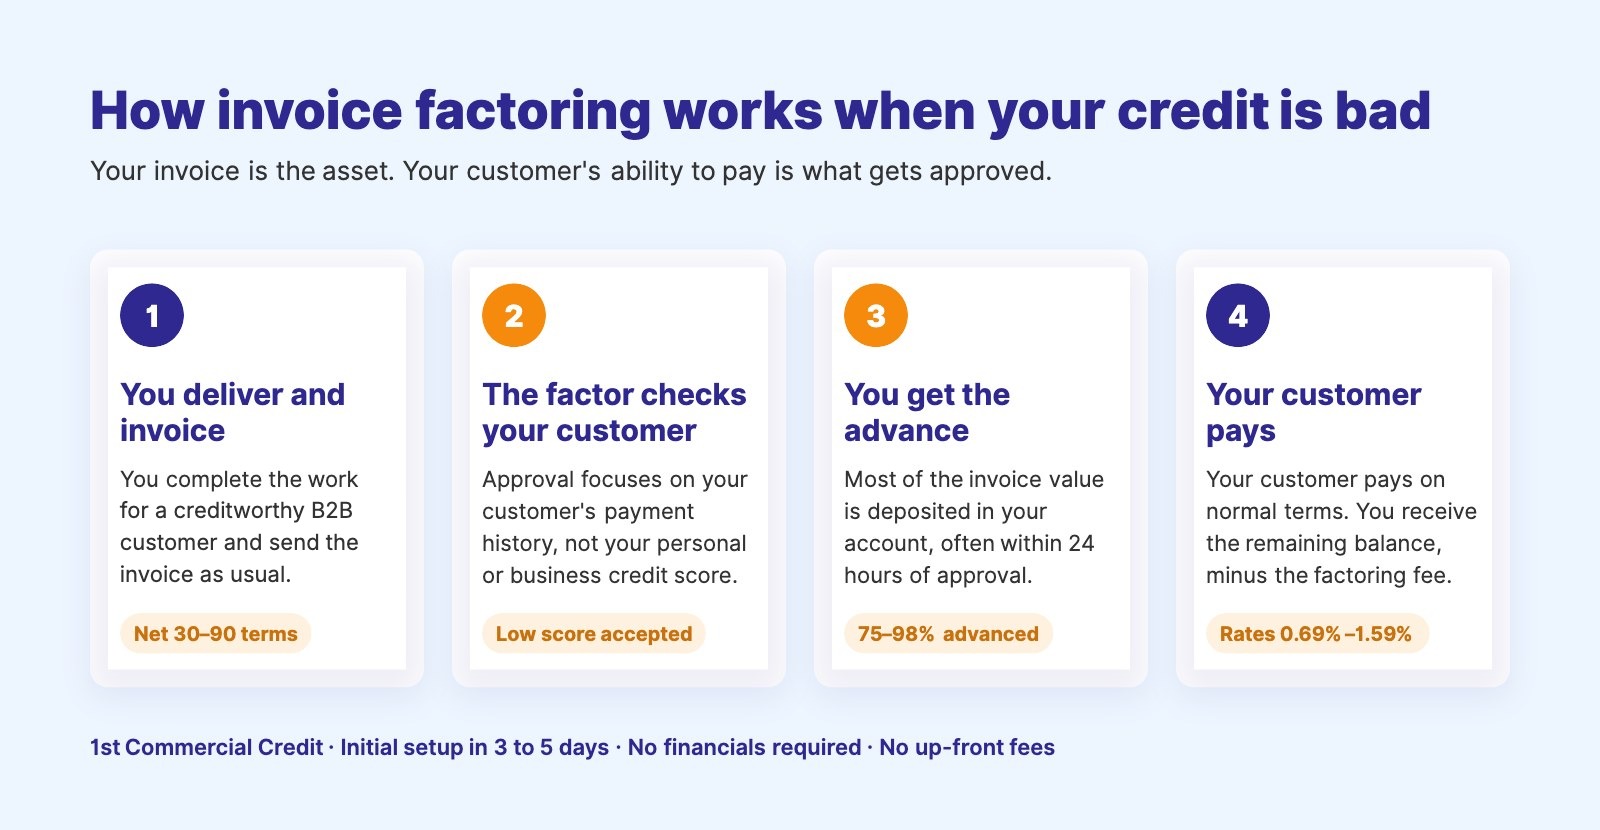
Yes. You can get funding with unpaid invoices even if your credit is bad. With invoice factoring, approval is based mainly on the credit of the customers who owe you money, not on your personal or business credit score. 1st Commercial Credit accepts low credit scores and advances 75% to 98% of the value of your approved invoices, depending on your industry, often within 24 hours of approval.
That is why factoring is usually the first option for business owners who have been turned down by a bank. Your unpaid invoices are already an asset. Factoring turns them into cash now instead of in 30, 60 or 90 days.
A bank loan is a bet on you: your credit score, your financial statements and your history of paying back debt. Invoice factoring is different. It is not a loan. You sell your unpaid invoices to a factoring company, and the factoring company gets paid when your customer pays the invoice.
So the main question for the factor is not "Will this business pay us back?" but "Will this business's customer pay the invoice?" If you invoice creditworthy companies or government agencies, a low credit score, a thin credit file or a recent bad year usually won't stop you from getting funded.
| What is reviewed | How much it matters | Why |
|---|---|---|
| Your customers' credit and payment history | High | Your customer is the one who pays the invoice, so their reliability is the main risk. |
| Quality of the invoices | High | Invoices must be for work already completed or goods already delivered, with no disputes. |
| Liens on your receivables | Medium | Existing liens (for example a tax lien) need to be addressed, but they are not always a dealbreaker. |
| Your personal or business credit score | Low | It is not the basis for approval. 1st Commercial Credit accepts low credit scores. |
| Your financial statements and time in business | Low | No financials are required, so new businesses and businesses coming off a loss can qualify. |
To use invoice factoring with bad credit, you typically need:
At 1st Commercial Credit, the initial setup takes 3 to 5 days, there are no up-front fees, and no financial statements are required.
If your credit is bad and you need cash, these are the options you are most likely to be offered. They work very differently.
| Option | Approval based on | Speed | Cost | Adds debt? | Best for |
|---|---|---|---|---|---|
| Invoice factoring | Your customers' credit | Often within 24 hours of approval, after a 3 to 5 day setup | Rates from 0.69% to 1.59% at 1st Commercial Credit | No, it is the sale of an asset | B2B businesses with unpaid invoices from reliable customers |
| Bad-credit business loan | Your credit and revenue | Days to weeks | Higher interest rates than standard loans | Yes | Businesses that need a lump sum |
| Merchant cash advance (MCA) | Your future card or bank deposits | Fast | Usually one of the most expensive options; repaid daily or weekly | Yes, in practice | Short-term emergencies when no other option is available |
| Bank line of credit | Your credit, financials and time in business | Weeks | Lowest cost if you qualify | Yes | Established businesses with strong credit |
The key difference: a loan or a merchant cash advance adds a payment you have to make whatever happens. Factoring gives you money you were already owed, earlier. For a deeper comparison, read how invoice factoring is different from a bank loan.
Here is an illustrative example. Actual advance rates and fees depend on your industry, your customers and your invoice volume.
Your credit score was never the deciding factor. What mattered was that your customer is a reliable payer.
A tax lien does not automatically disqualify you. 1st Commercial Credit has funded clients with tax liens, and the initial funding can sometimes be used to pay off the tax entity. Learn more about getting business funding while you have a tax lien.
Factoring may still be possible. Contact 1st Commercial Credit before you file, as there may be options available to you.
Because no financial statements are required and approval is based on your customers, a short history or a bad year is not a barrier on its own. If you want to keep collecting from your customers yourself, accounts receivable financing is a related option to discuss.
If you want protection in case a customer becomes insolvent, compare recourse vs. non-recourse factoring before you sign.
Yes. Factoring approval is based mainly on your customers' creditworthiness. 1st Commercial Credit accepts low credit scores.
Your credit may be reviewed as part of the setup, but it is not the basis for approval. The decision focuses on your customers and the quality of your invoices.
No. Factoring is not a loan, so it does not appear as debt on your balance sheet, and factoring companies don't report to the credit bureaus.
After a 3 to 5 day initial setup, invoices are typically funded the same day or within one business day once they are submitted and approved.
Typically 75% to 98% of the invoice value, depending on your industry. The rest, minus the factoring fee, is paid when your customer pays.
Yes. A criminal record can lead to a decline, but it doesn't always. We look at each case on its own, including what the offense was and how long ago it happened. The one exception is embezzlement: any history of embezzlement means an automatic decline.
1st Commercial Credit has helped more than 3,800 businesses turn unpaid invoices into working capital over 20+ years, including many that banks had turned down. If you have B2B invoices and customers who pay, your credit score shouldn't stand in the way. Request a quote or call 1 (800) 876-6071.

Low credit score accepted. Factor your unpaid invoices with 1st Commercial Credit and get the working capital your business needs, often within 24 hours of approval.


